
| User Roles |  Admin |  Staff contributor | ✗External contributor | ✗Pulse user |
The Financial Reporting Council (FRC) has completed its multi-year periodic review of UK and Republic of Ireland accounting standards. These updates represent the most significant shift in financial reporting since FRS 102 was introduced, and they bring UK GAAP into closer alignment with international financial reporting standards so that accounts remain relevant and transparent for all stakeholders. This article explains when the changes take effect, who they affect, and how Silverfin supports them.
Table of contents
- When do the changes take effect?
- Does Silverfin apply the new standards automatically, and can I adopt them early?
- Do I have to restate my 2025 accounts?
- Which clients are affected?
- What has changed?
When do the changes take effect?
The changes do not all take effect at the same time. You should prepare for two distinct implementation phases:
- Supplier finance arrangements: these rules apply to accounting periods beginning on or after 1 January 2025.
- The main periodic review (leases and revenue): most other changes, including the new lease and revenue models, apply to accounting periods beginning on or after 1 January 2026.
For example, a client with a 31 March year-end will not meet the main changes until their March 2027 accounts. This transition period gives you plenty of time to familiarise yourself with the new requirements and prepare your clients accordingly.
Early adoption is permitted for the 2024 Periodic Review changes, provided that you apply all amendments at the same time.
Does Silverfin apply the new standards automatically, and can I adopt them early?
- The updated standards apply automatically within Silverfin for all accounting periods starting on or after 1 January 2026. No manual action is required for these periods, because the platform defaults to the new requirements.
- Silverfin also lets you adopt these changes before the mandatory deadline. If you decide that early adoption is appropriate for a specific client, you can enable it directly within the platform.
- To activate the new standards early, go to the Accounts Workflow for the relevant period. From there, open the General Settings template and locate the Early Adoption toggle.
Do I have to restate my 2025 accounts?
When you move to the new rules on 1 January 2026, you do not necessarily have to rewrite your 2025 accounts. Recalculating years of old leases or complex revenue contracts is a significant task, so the FRC offers a simplified transition option that saves accountants from the burden of full retrospective restatement. This choice is available to all entities reporting under FRS 102, FRS 102 Section 1A, and FRS 105.
Within Silverfin, you can choose between a full retrospective approach and a simplified approach.
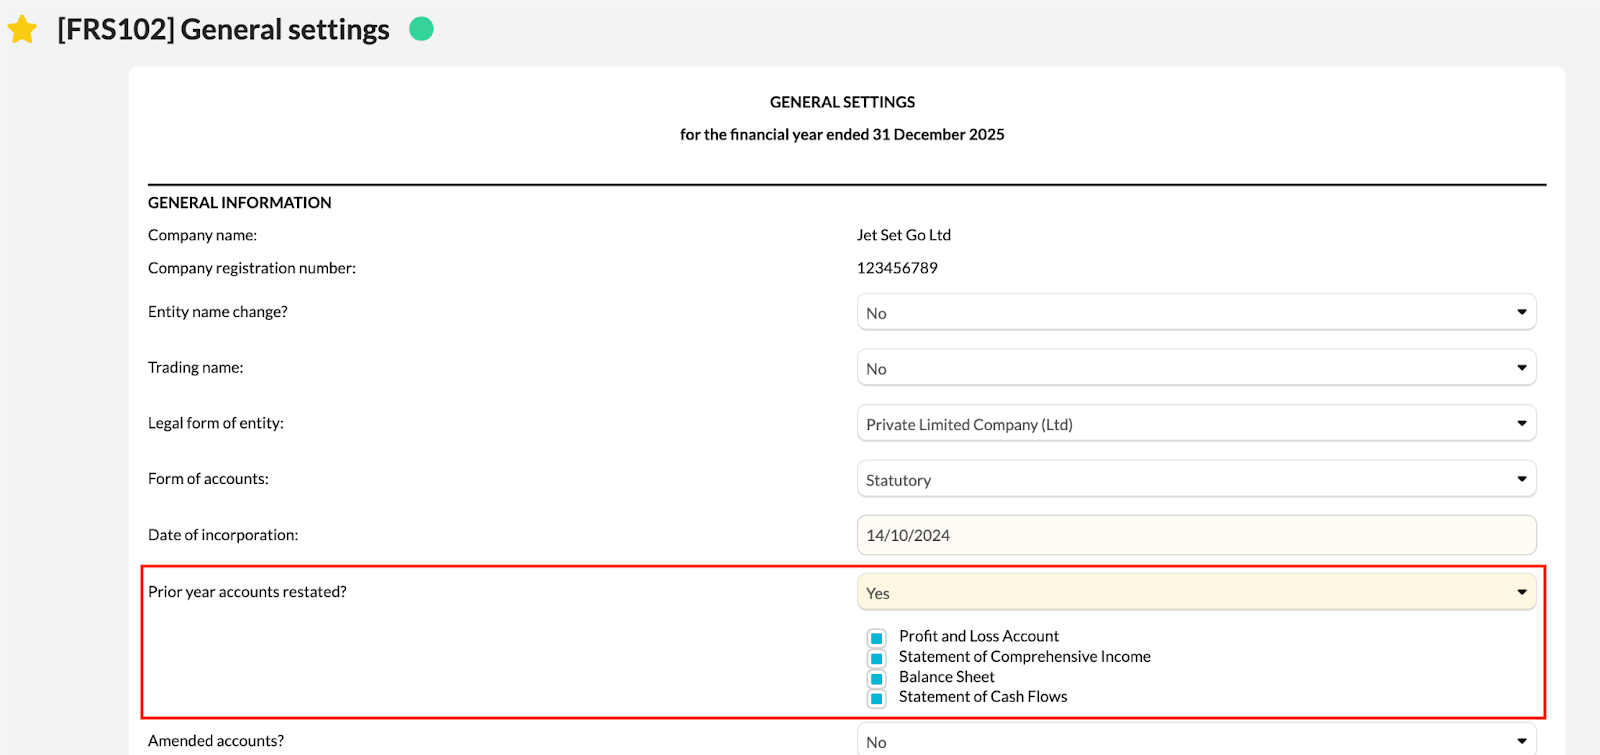
- The full retrospective method involves restating every figure in your accounts as if the new rules had always existed. To do this, go to the Accounts Workflow for the relevant period. From there, open the General Settings template and locate the Prior year accounts restated? toggle. You can then toggle which statements have been restated. See the screenshot below.
- The simplified method lets you keep the 2025 comparative figures as they are, and instead put any necessary adjustments through the opening reserves on 1 January 2026. To do this, create a journal adjustment.
Which clients are affected?
These updates affect all entities reporting under FRS 102 and FRS 105. For those using FRS 102 Section 1A, the review introduces several new mandatory disclosures that were previously only encouraged. Start assessing your client portfolios now to identify those with significant lease commitments or complex revenue contracts.
What has changed?
1. The Lease Revolution: Bringing Leases On-Balance Sheet
- The change: almost all leases, including office rent and vehicles, must now be recorded on the balance sheet. The old distinction between "operating" and "finance" leases has been removed for lessees. Exemptions remain for leases with a term of 12 months or less and leases of low-value assets.
- Context: previously, many leases were "off-balance sheet", meaning the full liability was not visible. The FRC is aligning FRS 102 with international standards (IFRS 16) so that a company's financial position more accurately reflects its long-term lease commitments.
- Applicable frameworks: this change applies to FRS 102 and FRS 102 Section 1A. It does not currently apply to micro-entities reporting under FRS 105, which continue to account for leases as an expense.
- Silverfin impact: you now need to recognise a Right-of-Use (ROU) Asset and a corresponding Lease Liability for nearly every lease. To support this, new working papers and accounts templates have been added to Silverfin to automate the calculation for the initial recognition of these assets, as well as the ongoing year-on-year interest and depreciation. These templates ensure that the correct balances flow directly into your financial statements while maintaining clear documentation of all lease judgements. For full information on the new updates in Silverfin, see Lease Liabilities and Right of Use Assets.
2. Revenue Recognition: The Move to the Five-Step Model
- The change: revenue can no longer be recognised based on a simple transfer of risks and rewards. Instead, you must follow the five-step process to decide exactly when and how much revenue to record.
- Context: the old rules could be interpreted in different ways, leading to inconsistency. This new framework (based on IFRS 15) ensures that revenue is only recognised when a company has actually "delivered" on the specific promises made to a customer.
- Applicable frameworks: this change applies to FRS 102, FRS 102 Section 1A, and FRS 105. All reporting entities must adopt the new five-step model, though the level of required disclosure varies.
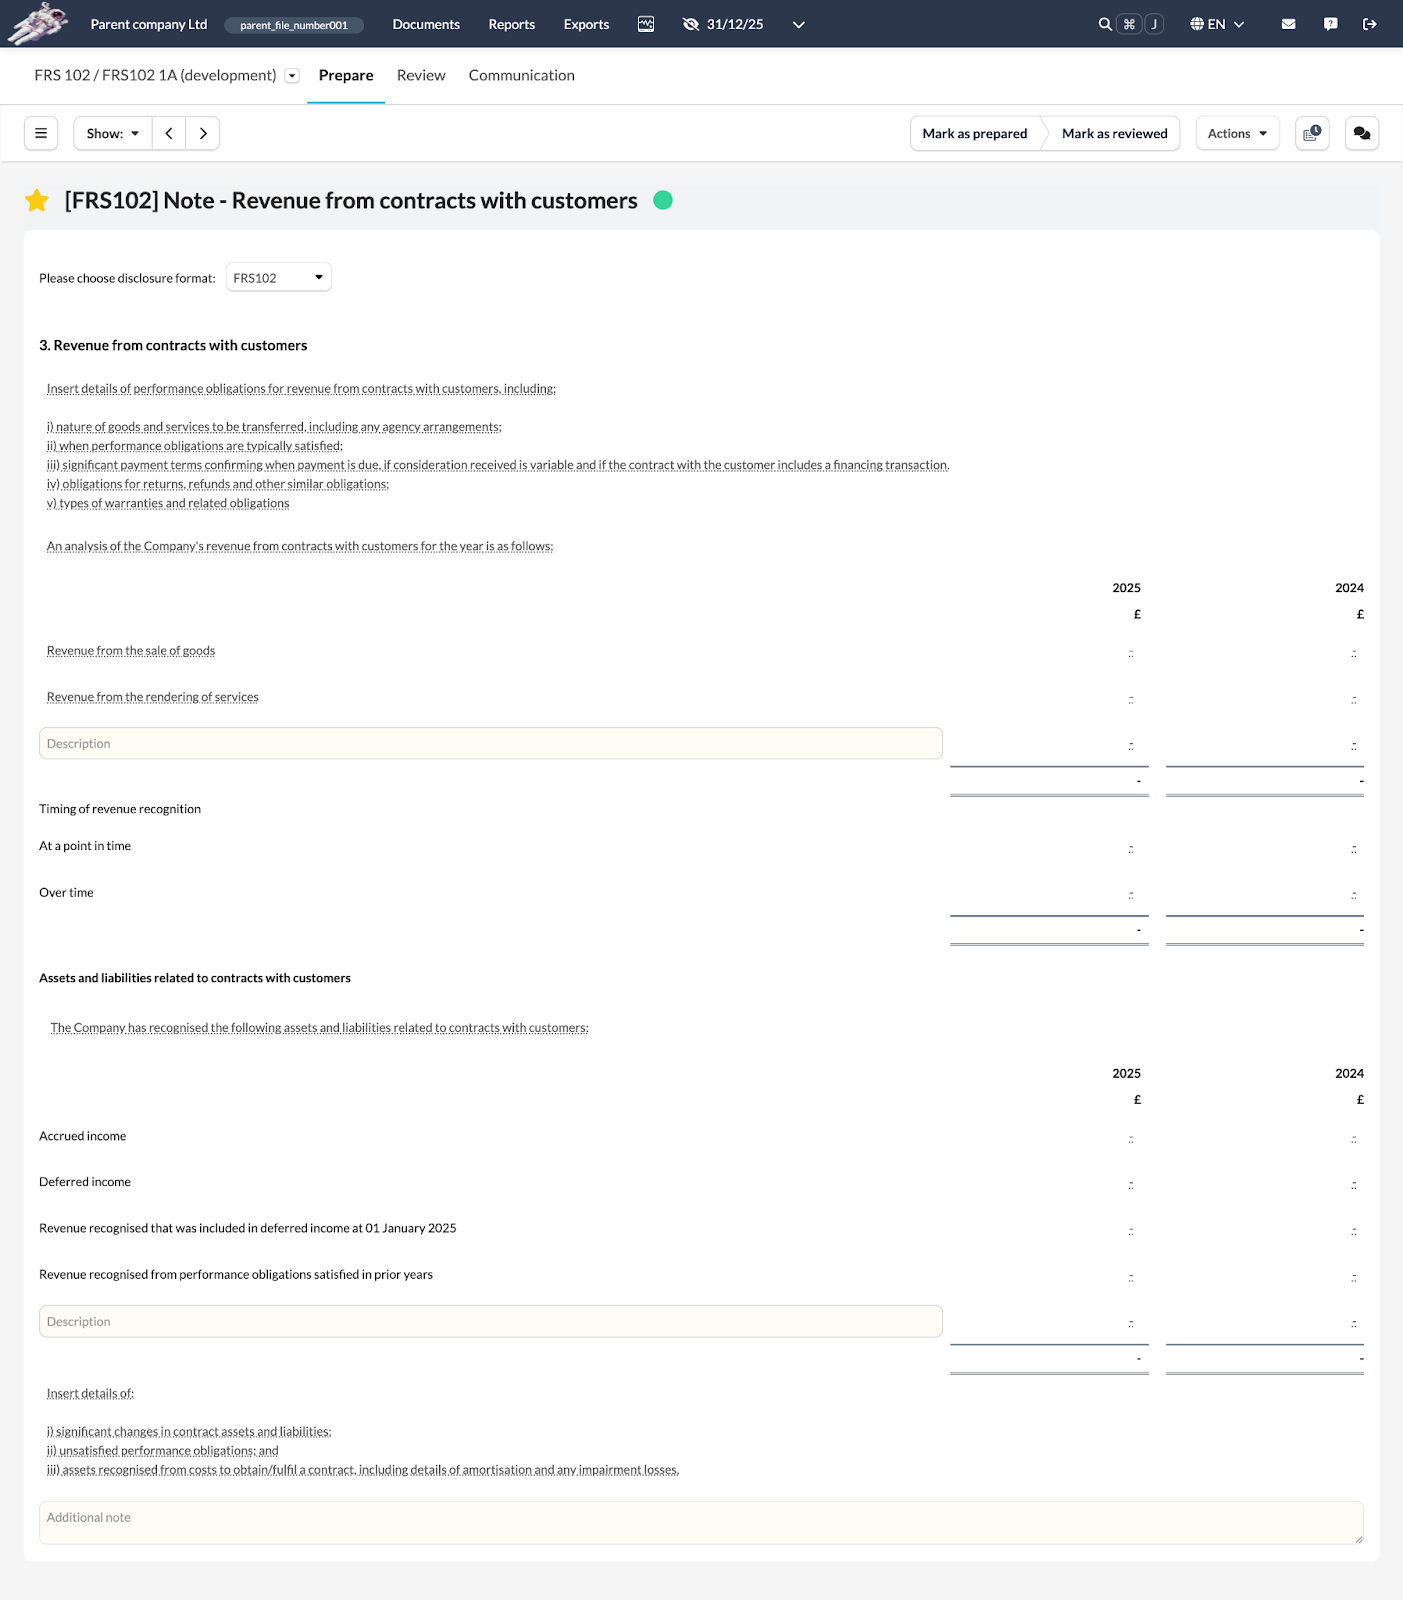
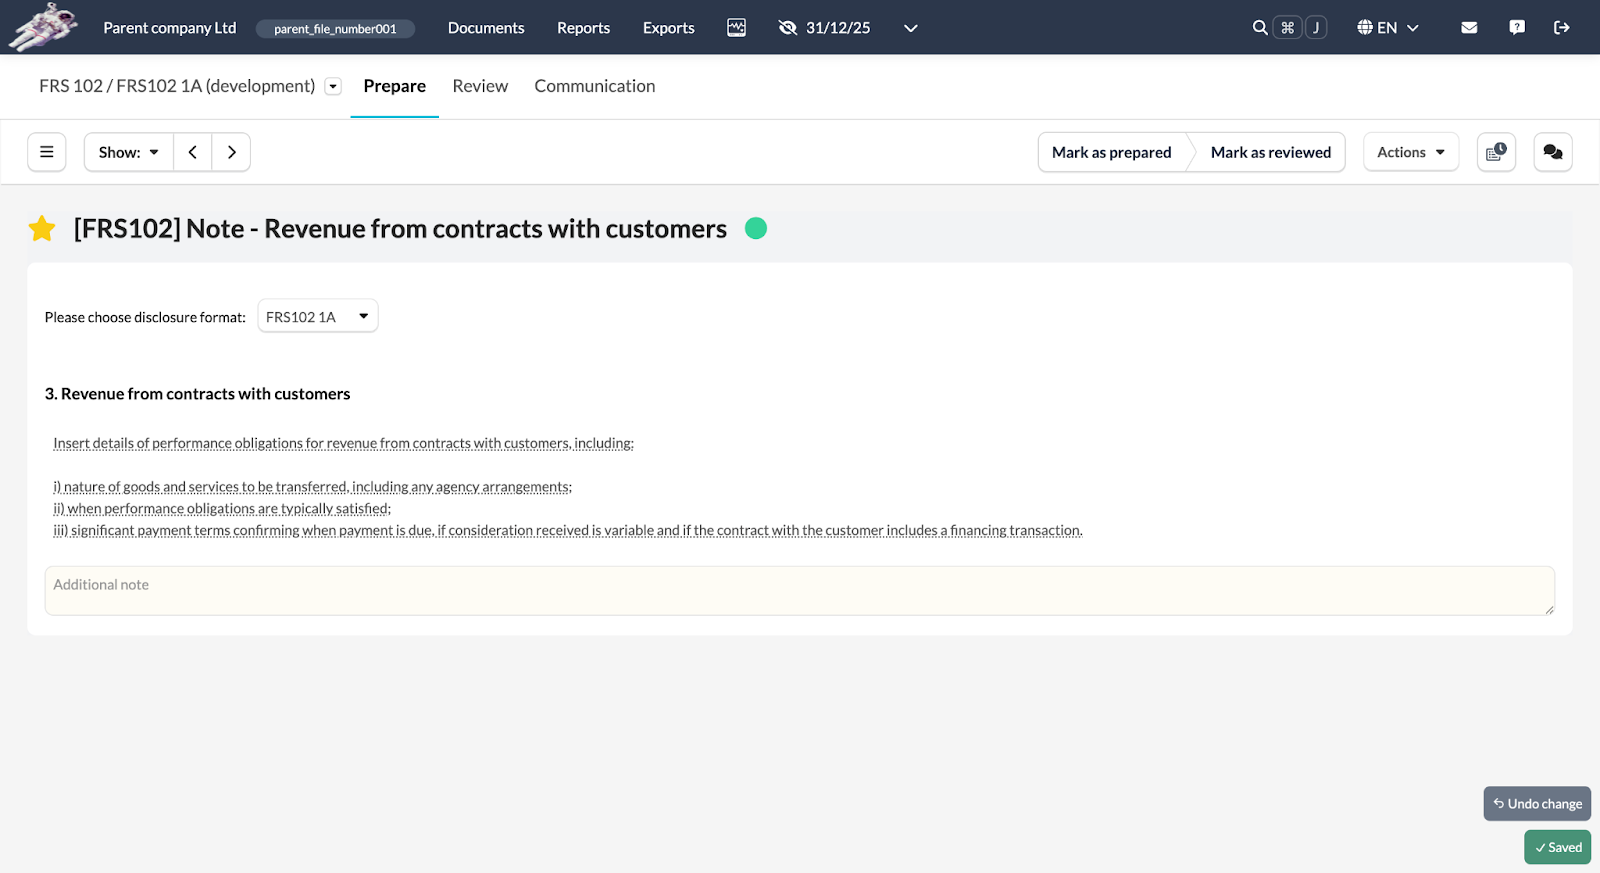
- Silverfin impact: you need to look closely at bundled contracts (such as software sold with hardware) to see if the timing of revenue recognition needs to be split. To support this, a new Revenue from contracts with customers accounts note has been added to Silverfin. For full FRS 102, this note provides all the necessary space for relevant quantitative and qualitative disclosures. For FRS 102 Section 1A, the note includes dedicated space to capture the details of performance obligations, ensuring that all entities meet the new transparency requirements.
FRS 102:
FRS 102 Section 1A:
3. Going Concern: From "Encouraged" to "Mandatory" Disclosures
- The change: for the first time, all companies, including those using Section 1A, must provide a specific note in their accounts explaining the basis on which they believe the company will continue to trade. You must explicitly state that management has looked ahead at least 12 months, and disclose the significant judgements or assumptions made.
- Context: in a volatile economy, the FRC wants to ensure that small company accounts are not silent on their survival. What was previously suggested is now a legal requirement, so that the accounts provide a "true and fair view".
- Applicable frameworks: this primarily affects FRS 102 Section 1A, as these disclosures were already standard practice for full FRS 102.
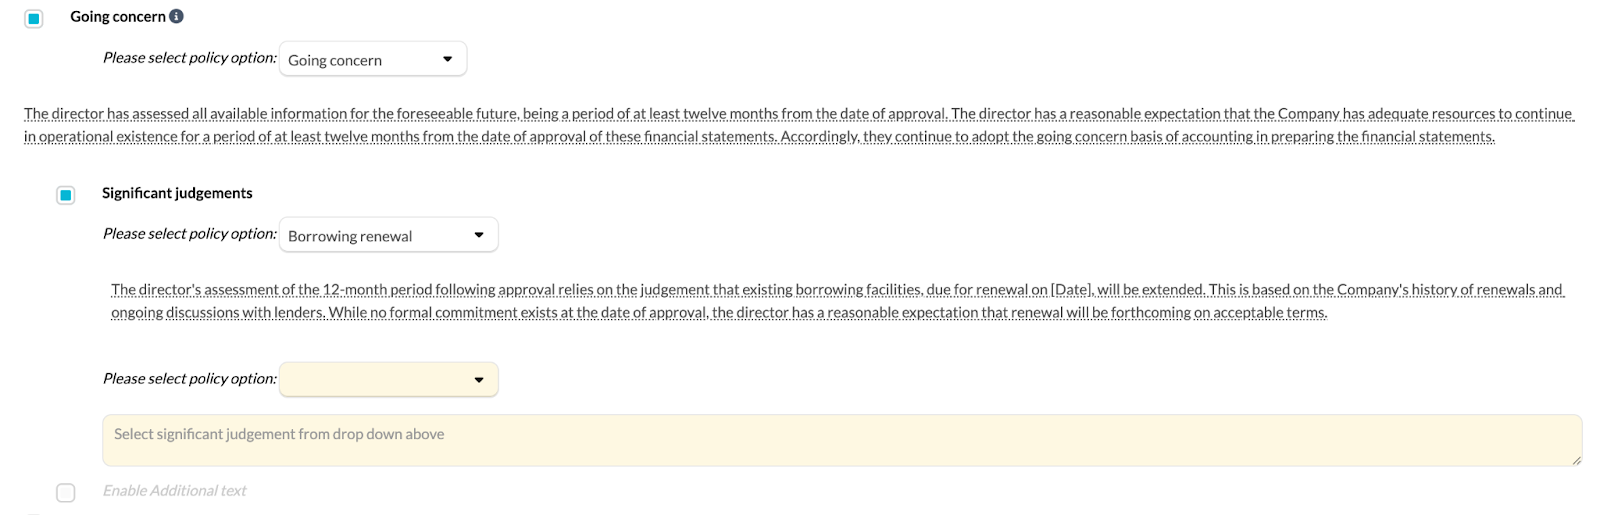
- Silverfin impact: the Going Concern section of the accounting policies note has been redesigned to accommodate these mandatory requirements. New drop-down menus let you select the overall going concern status and choose from a list of significant judgements. Additional text boxes are also available, so you can provide extra custom wording where specific detail is required.
4. Supplier Finance Arrangements: The "Early" Change (1 Jan 2025)
- The change: if a company uses "reverse factoring" or third-party finance to pay its suppliers, it must now clearly disclose these arrangements and the amount of debt involved.
- Context: these schemes can make a company's cash flow look healthier than it is, by hiding bank debt within "trade payables". This new rule brings these arrangements into the light, so users can understand the company's true liquidity.
- Applicable frameworks: this applies to FRS 102 and FRS 102 Section 1A. It does not currently apply to FRS 105.
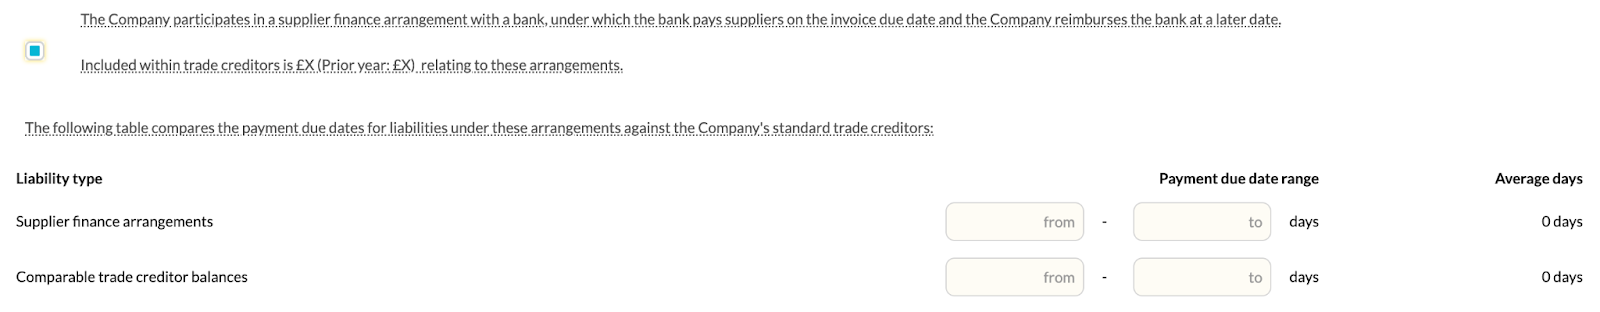
- Silverfin impact: you must disclose the total amount of liabilities sitting within these schemes and the typical payment terms. Note that this takes effect for periods starting 1 January 2025. To support this, a new checkbox has been added to the bottom of the Creditors: amounts falling due within one year note. Enabling this checkbox lets you separate out the necessary disclosure, and provides dedicated input fields to record the specific terms of the arrangement.
5. Section 1A "Small Entities": New Mandatory Disclosures
- The change: the "reduced disclosure" era for small companies is ending. You are now required to provide more detailed notes on areas such as share-based payments, deferred tax, and dividends.
- Context: the FRC found that many small company accounts were too brief to be useful. By making these notes mandatory, it is raising the standard of reporting to ensure small company accounts are genuinely "true and fair".
- Applicable frameworks: this section applies exclusively to FRS 102 Section 1A.
- Silverfin impact:to ensure compliance with the new standard, Silverfin includes the relevant disclosures as default requirements, so you no longer need to override and include them. These include, but are not limited to:
- Share-based payments: you must now provide details on any arrangements, including the relevant profit and loss charges and liability values.
- Deferred tax: a full breakdown of the deferred tax balance is now required.
- Dividends: you must disclose dividends declared and paid during the period for each share type.
- Related parties: more transparency is required for transactions with anyone closely linked to the business.